How to Set Your First Investment Goal
Getting Started With Investing — Part 2
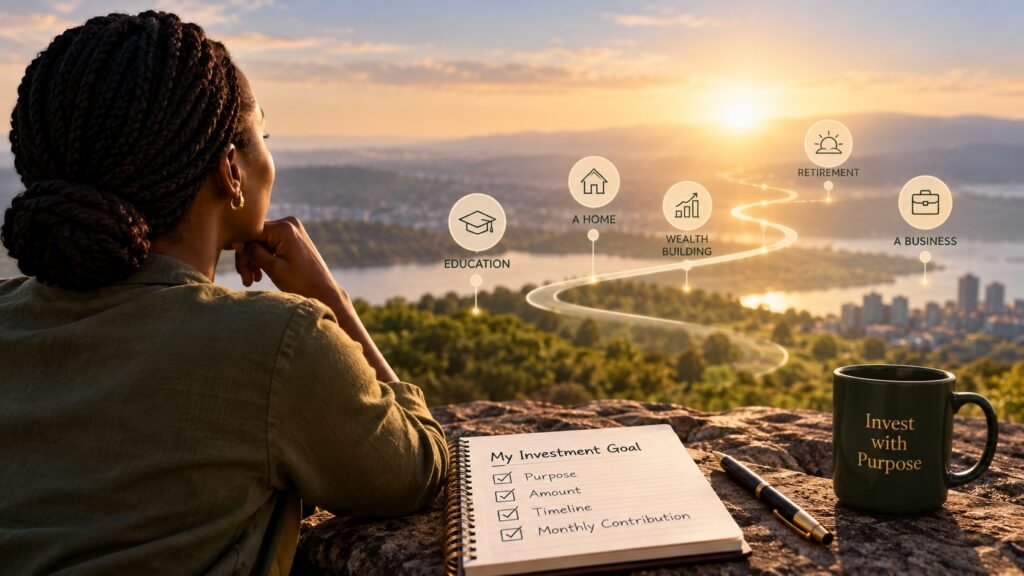
You have decided that you want to start investing.
Great.
So what should you invest in?
A money market fund? Treasury bonds? Shares? Property? A unit trust?
Surprisingly, that may be the wrong question to start with.
Before deciding where to invest, there is a more important question:
What are you investing for?
That question is the foundation of goal-based investing.
Because investing without a goal can easily become a collection of products rather than a financial plan.
Start With the Destination
Think about planning a journey.
Before choosing whether to drive, fly or take a train, you first need to know where you are going.
Investing works much the same way.
Your investment goal helps determine:
- How much money you will need.
- When you will need it.
- How much you may need to invest today or every month.
- How much investment risk you can reasonably take.
- What types of investments may be appropriate.
The investment product therefore comes after the goal, not before it.
Turn a Wish Into a Goal
Many of us have financial aspirations:
“I want to educate my children well.”
“I want to own a home.”
“I want to retire comfortably.”
“I want to build wealth.”
These are important aspirations, but they are not yet investment goals.
A useful investment goal needs three things:
A purpose. A number. A date.
Instead of:
“I want to save for my child’s education.”
Try:
“I want to accumulate KES 5 million for my child’s university education in 10 years.”
Instead of:
“I want to prepare for retirement.”
Try:
“I want to build an investment portfolio capable of providing KES 150,000 per month when I retire at age 60.”
Suddenly, the aspiration becomes something you can actually plan for.
Ask Yourself Five Questions
When setting your first investment goal, start with these five questions.
1. What exactly am I investing for?
Be specific.
It could be education, retirement, buying a home, starting a business, building an emergency reserve, creating passive income or achieving financial independence.
The clearer the purpose, the easier it becomes to build—and remain committed to—a plan around it.
2. How much will I need?
This is where your goal begins to move from an idea to a number.
If your goal is your child’s university education, for example, you need to estimate what that education is likely to cost when the child actually gets to university.
If your goal is retirement, you need to think about the income you would like your investments to provide when you stop working.
And remember: today’s cost may not be tomorrow’s cost.
Inflation matters.
A university education costing KES 3 million today could cost considerably more ten or fifteen years from now.
Rather than trying to work all this out manually, you can use the Rubiani Wealth Calculators to begin translating your financial aspiration into an estimated investment target.
👉 Try the Rubiani Wealth Calculators:
https://rubianiwealth.com/calculators/
3. When will I need the money?
Time is one of the most powerful variables in investing.
A goal that is two years away should generally be approached differently from one that is twenty years away.
Why?
Because time affects both your ability to compound returns and your ability to tolerate short-term fluctuations.
It also affects how much you need to invest today.
The earlier you start, the more time your money potentially has to compound—and the less pressure there may be on your monthly contribution.
Curious what difference starting now rather than five years from now could make?
Run your goal through the Rubiani Wealth Calculators and compare the numbers.
👉 https://rubianiwealth.com/calculators/
4. How much can I realistically invest?
Once you know your target and timeline, you can work backwards.
Suppose your goal requires KES 5 million in ten years.
The practical question becomes:
How much would I need to invest today—or every month—to work towards that target?
This is where investing becomes real.
And you don’t need to reach for a spreadsheet.
Use the Rubiani Wealth Calculators to test different scenarios.
What happens if you invest KES 10,000 per month?
What about KES 20,000?
What if you start with a lump sum and continue with monthly contributions?
What happens if you give yourself another three years?
👉 Explore your numbers here:
https://rubianiwealth.com/calculators/
You may discover that your current monthly contribution is sufficient.
Or that you need to:
- increase your monthly investment,
- extend your timeline,
- adjust the target, or
- combine an initial lump sum with regular contributions.
The important thing is that you are now making decisions based on a goal and a plan, rather than guesswork.
5. How Much Risk Can This Goal Afford?
Notice the wording.
Not simply:
“How much risk can I tolerate?”
But:
“How much risk can this goal afford?”
These are not always the same thing.
You may personally be comfortable taking significant investment risk. But if the money is required for your child’s school fees six months from now, that particular goal may not have enough time to recover from a significant market decline.
Conversely, retirement savings for someone with twenty-five years until retirement may have considerably more time to ride through market cycles.
Risk should therefore be considered in the context of the goal and its timeline.
One Person Can Have Several Investment Goals
Most of us are not investing for just one thing.
You might simultaneously be investing for:
- an emergency reserve,
- children’s education,
- a home deposit,
- passive income, and
- retirement.
These goals have different amounts, timelines and priorities.
And that means they may require different investment strategies.
This is one reason why asking:
“What is the best investment?”
can be misleading.
There may be no universally “best” investment.
The better question is:
“What investment is appropriate for this particular goal?”
Your First Goal Does Not Need to Be Huge
If you are just beginning your investment journey, don’t allow the size of the ultimate goal to discourage you.
Start with one meaningful goal.
Define it.
Put a number to it.
Give it a timeline.
Calculate what it will take to get there.
Then begin.
A KES 10 million target is ultimately built from the first KES 10,000, KES 20,000 or KES 50,000 invested consistently towards it.
The important shift is moving from:
“I should start investing.”
to:
“I am investing KES X every month towards Y goal, which I want to achieve by Z date.”
That is when investing becomes intentional.
Your Weekend Wealth Challenge
This weekend, choose one financial goal you would genuinely like to achieve.
Then complete these four statements:
My goal is: ______________________________
I will need approximately: KES __________________
I want to achieve it by: __________________
I can currently invest: KES __________________ per month
Then take those numbers and put them to work.
👉 Visit the Rubiani Wealth Calculators and see what your goal could require of you:
Change the amount.
Change the timeline.
Change the monthly contribution.
See what happens.
Because sometimes the most powerful moment in an investment journey is when “one day” finally becomes a number and a date.
And once you have your goal, the next question becomes:
What kind of investment risk should you take to get there?
That is where we will pick up in Part 3 of Getting Started With Investing: Understanding Risk and Return.
Rubiani Wealth Series | Getting Started With Investing
Part 1: What Every First-Time Investor Should Know Before Investing
Part 2: How to Set Your First Investment Goal
Coming Next: Understanding Risk and Return
At Rubiani Capital, we believe investing should begin with your goals—not with an investment product.
Define the goal. Do the numbers. Build the plan. Invest with purpose.