What Every First-Time Investor Should Know Before Investing
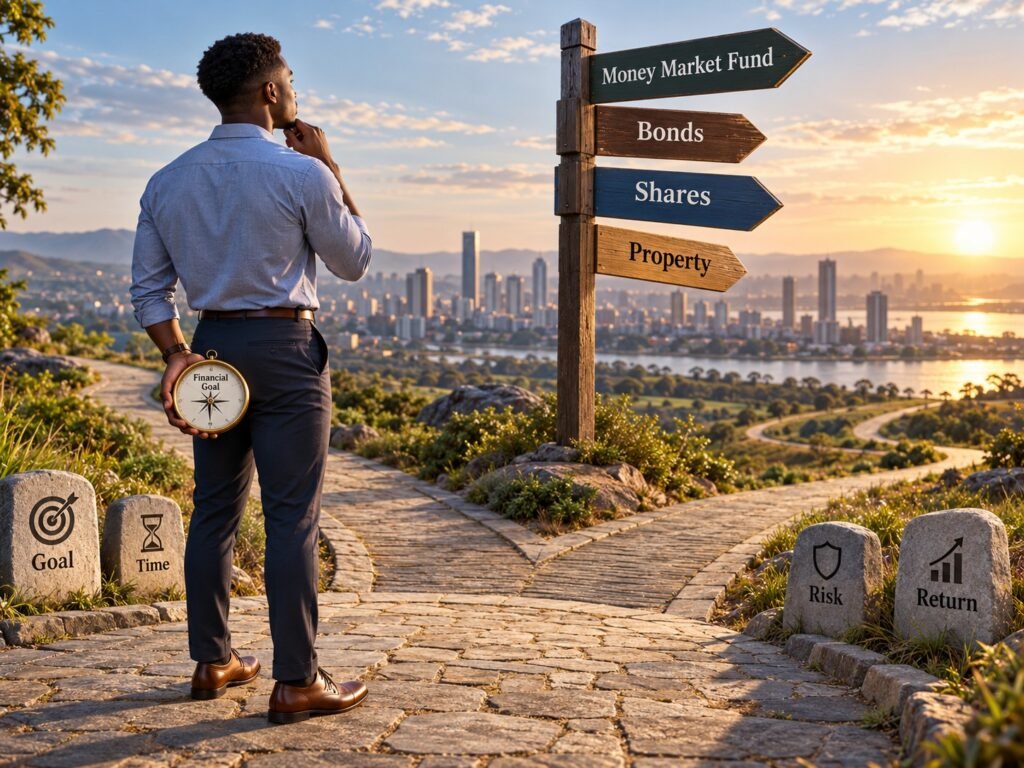
For many people, the hardest part of investing is simply getting started.
You may have heard friends discussing money market funds, Treasury bonds, shares, property, SACCOs or other investment opportunities. You may have seen attractive returns advertised online. And perhaps you have reached the point where you are thinking:
“I have some money available. Where should I invest it?”
It is a perfectly reasonable question.
But it may not be the best question to start with.
Before deciding where to invest, a first-time investor should first understand why they are investing, what they want the money to achieve, when they will need it, and how much risk they are prepared to take.
Investing is not simply about finding the product offering the highest return. It is about making deliberate financial decisions that move you towards your goals.
Here are some important principles every first-time investor should understand.
1. Start With the Goal, Not the Investment Product
There is rarely one investment that is simply “the best.”
The appropriate investment depends on what you are trying to achieve.
You could be investing to:
- Build an emergency reserve.
- Pay school fees several years from now.
- Purchase a home.
- Create an additional source of income.
- Accumulate capital for a business.
- Prepare for retirement.
- Achieve financial independence.
- Preserve wealth for the next generation.
Each of these goals may require a different investment strategy.
For example, money that you may need within the next year should generally be approached differently from money being accumulated for retirement twenty years from now.
The first question should therefore be:
“What am I investing for?”
Once the destination is clear, it becomes much easier to identify an appropriate route.
2. Understand Your Investment Time Horizon
Your investment horizon is simply the amount of time between today and when you expect to need the money.
A goal may be:
Short term: perhaps within one to three years.
Medium term: perhaps three to seven years away.
Long term: potentially ten, twenty or even thirty years into the future.
Time matters because different investments behave differently.
Some investments provide greater stability and liquidity but potentially lower long-term returns. Others may fluctuate significantly in the short term but provide stronger growth potential over longer periods.
A long investment horizon can therefore allow an investor to consider opportunities that may not be appropriate for money required in the near future.
Always match the investment to the goal’s timeline.
3. Return Is Only One Part of the Investment Decision
One of the most common mistakes first-time investors make is comparing investments purely on the basis of their advertised return.
A statement such as:
“This investment earns 12% while that one earns 9%”
does not, by itself, tell you which investment is better.
You should also understand:
- The level of risk involved.
- How quickly you can access your money.
- Whether the return is guaranteed or variable.
- Whether the quoted return is before or after fees and taxes.
- How the investment has performed over time.
- Who manages and safeguards the money.
- Whether the investment is regulated.
A higher potential return will often come with additional risk or restrictions.
The better question is therefore not:
“Which investment has the highest return?”
but:
“What return is appropriate for the level of risk, liquidity and time horizon associated with my goal?”
4. Understand Risk Before You Invest
Every investment carries some form of risk.
Even investments generally considered conservative are exposed to risks such as inflation, interest-rate movements, liquidity constraints, credit risk or changes in market conditions.
Investment risk does not automatically mean that an investment is bad.
It means that you should understand what could cause the value or expected return of your investment to change.
Before investing, ask yourself:
How much loss or fluctuation could I financially withstand?
And equally importantly:
How much fluctuation could I emotionally withstand without panicking and abandoning my investment strategy?
An investment strategy should be appropriate both for your financial circumstances and for your personal tolerance for risk.
5. Do Not Invest Money You May Need Immediately
Investing should not leave you financially vulnerable.
Before committing significant amounts to longer-term investments, consider whether you have sufficient funds available for immediate needs and unexpected expenses.
Without an emergency reserve, an investor may be forced to withdraw from a long-term investment at the wrong time simply because an unexpected expense has arisen.
Liquidity therefore matters.
A healthy financial plan normally balances:
money for today, money for emergencies and money for the future.
6. Consistency Can Be More Powerful Than Waiting for a Large Amount of Money
Many people postpone investing because they believe they need a substantial amount of money to begin.
But wealth is often accumulated through consistent investing over long periods rather than through one large investment.
For example, regularly investing a manageable portion of your income can allow you to benefit from:
- Financial discipline.
- Compounding over time.
- Reduced temptation to spend surplus income.
- Gradual accumulation of meaningful capital.
The question should therefore not always be:
“How much money do I need before I can start?”
Sometimes the better question is:
“What amount can I comfortably and consistently invest towards this goal?”
Starting with a sustainable amount and increasing it as your income grows can be far more effective than continually waiting for the “right time.”
7. Understand the Power of Compounding
Compounding occurs when investment earnings begin generating additional earnings.
Over sufficiently long periods, this can become one of the most powerful forces in wealth creation.
Consider two people who ultimately contribute similar amounts of money, but one begins investing significantly earlier than the other.
The person who starts earlier may accumulate considerably more wealth simply because their money has had more time to compound.
This is why one of the greatest advantages a young investor has is not necessarily a large income.
It is time.
The earlier your money begins working towards your goals, the longer compounding has an opportunity to work for you.
8. Inflation Matters
Keeping money safe is important.
But preserving the purchasing power of that money is equally important.
If the cost of living increases over time while your money earns little or no return, the amount in your account may remain unchanged while what that money can actually purchase gradually declines.
This is one reason investing becomes important for longer-term goals.
The objective is not simply to accumulate money.
It is to build sufficient future purchasing power to achieve the goal for which the money is being set aside.
9. Know Who You Are Investing With
Before transferring your money to any investment provider, conduct basic due diligence.
Understand:
- Who the institution is.
- What regulatory framework it operates under.
- Who actually holds your money or investment assets.
- What investment product you are entering.
- What fees apply.
- What the withdrawal process is.
- What documentation you will receive.
- Where you can obtain independent information about the provider.
Be particularly cautious where an investment promises unusually high or guaranteed returns with little explanation of the underlying investment or associated risk.
If you do not understand how your money generates the stated return, ask questions before investing.
A legitimate investment provider should be willing to explain the structure clearly.
10. Understand Fees, Taxes and the Return You Actually Receive
The return advertised by an investment product may not necessarily be the amount that ultimately reaches you.
Depending on the investment, there may be:
- Management fees.
- Advisory or platform fees.
- Transaction costs.
- Custody charges.
- Taxes.
- Other administrative expenses.
These costs may appear small individually, but over long investment periods they can materially affect the amount you accumulate.
A first-time investor should therefore understand the difference between the headline return and the net return actually earned.
11. Diversification Matters
You have probably heard the expression:
“Do not put all your eggs in one basket.”
That is essentially the principle behind diversification.
Rather than placing all your wealth into a single investment, company, sector or asset class, an investor may spread investments across different areas.
The objective is not to eliminate risk completely.
It is to reduce the likelihood that one poor-performing investment significantly damages your entire financial position.
As your investment portfolio grows, diversification becomes increasingly important.
12. Avoid Investing Based Purely on Hype
Investment opportunities often become most attractive to the public after they have already received substantial attention.
A particular share may be trending.
Everyone may suddenly be discussing property.
A new investment product may be circulating on social media.
Friends may claim to be earning extraordinary returns.
That does not necessarily mean you should invest.
Before following the crowd, return to your investment framework:
Does this investment align with my goal?
Do I understand the risks?
Is the expected return reasonable?
How easily can I access my money?
How does it fit within my overall portfolio?
A good investment for somebody else may be completely inappropriate for you.
13. Investing Is a Journey, Not a Transaction
Perhaps the most important lesson for a first-time investor is that investing is rarely a one-off event.
Your circumstances will change.
Your income may grow.
Your family responsibilities may change.
Your goals may evolve.
Markets will rise and fall.
New opportunities will emerge.
An effective investment strategy should therefore be reviewed periodically and adjusted when circumstances genuinely require it.
The objective is not to predict every market movement.
It is to remain consistently aligned with your financial goals.
Before You Invest, Ask Yourself These Five Questions
Before making your first investment, take a moment and answer:
1. What financial goal am I trying to achieve?
2. When will I need the money?
3. How much can I invest consistently without compromising my immediate financial needs?
4. What level of investment risk am I comfortable taking?
5. Do I fully understand the investment, its fees, its risks and how I can access my money?
If you cannot confidently answer these questions, you may not need another investment product yet.
You may simply need a clearer investment plan.
The Rubiani Perspective
At Rubiani Capital, we believe investing should begin with empowerment and clarity.
Investment products are tools. Their value depends on how effectively they help an investor achieve a specific financial objective.
That is why we advocate a goal-based investment approach — beginning with where you are today, defining where you want to go, understanding the gap between the two, and then identifying an appropriate investment journey to help you get there.
Because ultimately, successful investing is not about being able to say:
“I invested.”
It is about being able to say:
“I achieved the financial goal I invested for.”
Rubiani Wealth Series
Empowering you to make informed investment decisions and intentionally build towards your financial goals.
This article is for general financial education and does not constitute individualized investment advice. Investment decisions should take into consideration an investor’s objectives, financial circumstances, risk tolerance and applicable product terms.