Quickmart’s proposed IPO: A new opportunity for Kenyan Investors
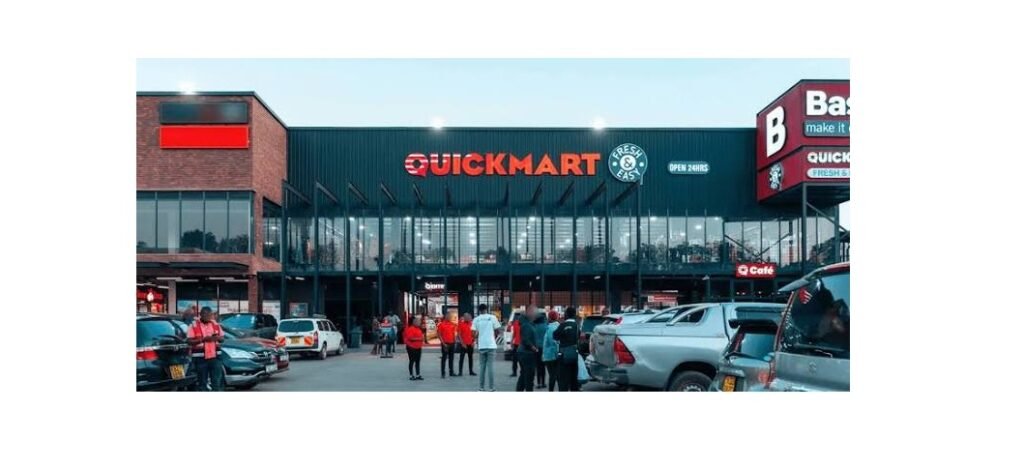
For many Kenyans, Quickmart is already part of everyday life. Its proposed listing on the Nairobi Securities Exchange (NSE) could now give shoppers an opportunity to become shareholders. It is an exciting prospect for a market seeking more investment choices. But familiarity with a supermarket is only the beginning of an investment decision.
Quickmart’s owners propose to sell 2 billion shares, representing 50% of the company, with an option to sell a further 7.5% if demand warrants it. The offer and listing remain subject to regulatory approval. Crucially, this is an offer for sale: the proceeds from shares sold will go to existing shareholders, rather than providing new capital to Quickmart.
Why the listing matters
A Quickmart listing would add a sizeable consumer retail business to an NSE where investors have relatively few comparable choices. It would also give the public a chance to participate in the future of a Kenyan business they can observe firsthand. For the wider market, a successful offer could encourage other privately held companies to consider public ownership. These are potential benefits, rather than guaranteed outcomes.
The business has a substantial operating footprint, with more than 72 stores, five million monthly customer visits and over 700 suppliers. That scale is relevant, but store growth alone does not establish that a share is attractively priced. Investors need to see whether expansion has translated into durable profits and cash flow.
The Adenia chapter
Private equity firm Adenia Partners has played a significant role in Quickmart’s growth. After investing in Tumaini Self Service, Adenia invested in Quickmart in 2019. The two businesses were brought together under the Quickmart brand, followed by a period of more structured expansion and professional management.
The proposed listing would give Adenia and the other existing owners a route to sell part of their holdings. It is therefore useful to understand who is selling, how much they will retain and what the ownership structure will look like after listing. The proposed sale is described as a proportionate partial exit by the shareholder group; if the additional shares are sold in full, the group’s retained stake would be approximately 42.5%.
A private equity exit is neither a reason to reject the offer nor a reason to buy it. Such investors typically seek an eventual route to realise their investment. The more important question for incoming shareholders is whether Quickmart’s prospects, governance and offer price make the investment attractive from this point forward.
The investment question: what are you paying for?
Quickmart offers exposure to everyday consumer spending. An established store network, supplier relationships and a recognisable brand may support its ability to grow. The proposed dividend policy is another point of interest: the company intends to target a payout of approximately 80% of annual profit after tax, subject to its financial position, growth needs and board discretion. A target, however, is not a guaranteed dividend.
The risks deserve equal attention. Supermarkets operate on tight margins. Rent, staff costs, stock losses, competition and pressure on household budgets can all affect returns. Investors should also examine lease commitments and the cash needed to open and maintain stores. A strong sales story can coexist with weaker cash generation.
Our investment position is therefore one of interest, subject to price and disclosure. Before deciding whether to participate, we would review the approved Information Memorandum for:
- The final offer price and the valuation it implies relative to earnings and cash flow.
- Profit trends, margins and cash generation across several years.
- Lease obligations, working capital and the cost of planned expansion.
- The selling shareholders’ stakes and the ownership and governance arrangements after listing.
- Whether the prospective dividend is sustainable alongside the company’s growth plans.
There is a meaningful distinction between liking a business and buying its shares at a price that suits your goals. A compelling company can still be a poor investment if the entry price assumes more growth than it can deliver. Equally, short-term excitement around a new listing should not replace a view of how the investment fits within a diversified portfolio.
Quickmart’s proposed IPO is a welcome opportunity to examine a business close to Kenyan consumers. We look forward to reviewing the approved offer documents, assessing the price against the potential returns and risks, and sharing our investment position once the full terms are available.